
An insurance claim denial versus fraud allegation presents two different questions. A coverage dispute asks whether the policy covers a particular loss, whether an exclusion or condition applies, and how the loss should be valued. A fraud allegation asks whether someone knowingly made or prepared a materially false, incomplete, or misleading statement with the required intent. A denial does not by itself prove fraud.
The distinction matters because the documents, decision-makers, and risks may be different. A policyholder can disagree with an insurer about causation, scope of repairs, valuation, or an exclusion without being accused of a crime. At the same time, a claim can move from an ordinary adjustment into a special-investigations or government inquiry. The letter or request in front of you should be classified before you respond.
What a coverage dispute usually asks
Coverage analysis begins with the policy in effect on the date of loss, including declarations, endorsements, exclusions, deductibles, duties after loss, and definitions. The factual questions may include what caused the damage, when it occurred, whether notice was timely, what property was affected, and what amount is supported by inspections or estimates.
A denial, partial denial, reservation-of-rights letter, or disagreement over repair scope generally addresses the insurance contract. Florida’s unfair-claim-settlement statute includes standards concerning reasonable investigations and written explanations that connect a denial to the policy, facts, or applicable law. The exact duties and remedies depend on the policy and claim type, but the current provisions can be reviewed in section 626.9541, Florida Statutes.
None of those issues necessarily answers whether a claimant acted dishonestly. Two professionals may reach different repair estimates. A policy term may be disputed. New damage may be difficult to separate from prior wear. Those conflicts require evidence and policy analysis rather than an assumption that an unpaid claim is criminal.
What turns the inquiry toward alleged fraud
Florida’s insurance-fraud statute addresses specified statements or claim activity made knowingly and with intent to injure, defraud, or deceive an insurer. It also requires the information at issue to be material in the circumstances described by the statute. The full current language appears in section 817.234, Florida Statutes.
That is different from simply showing that a statement was inaccurate. A date may have been estimated, an invoice misunderstood, a form completed by another person, or a contractor’s scope disputed. Those possibilities are not automatic defenses, but they illustrate why counsel examines knowledge, intent, materiality, authorship, and context instead of treating every inconsistency as proof of fraud.
Signals that the matter may have changed include contact from a special investigations unit, an accusation that photographs or invoices were altered, a request focused on who prepared a document, a referral to the Florida Department of Financial Services, contact from law enforcement, or a subpoena. A generic request for more claim information is not identical to any of those events.
Read the request before deciding how to respond
Identify who sent the communication and what it requires. An adjuster’s request, an examination-under-oath notice, a recorded-statement request, an agency inquiry, and a subpoena have different sources of authority and different consequences. Do not ignore a deadline, but do not assume that every request requires an immediate unscripted interview.
An insurance policy may impose cooperation and documentation duties. A government investigator, however, may be gathering evidence for a criminal case. When those processes overlap, a response intended to resolve coverage can become part of a broader record. Counsel can review the policy, the wording of the request, and the status of the investigation before advising what must be provided and how.
Do not lie, guess, submit a replacement document as though it were an original, or ask another person to align an account. If an earlier answer was wrong, preserve it and tell counsel exactly what happened. A rushed correction without context can create a second ambiguity.
Build the claim file from original records
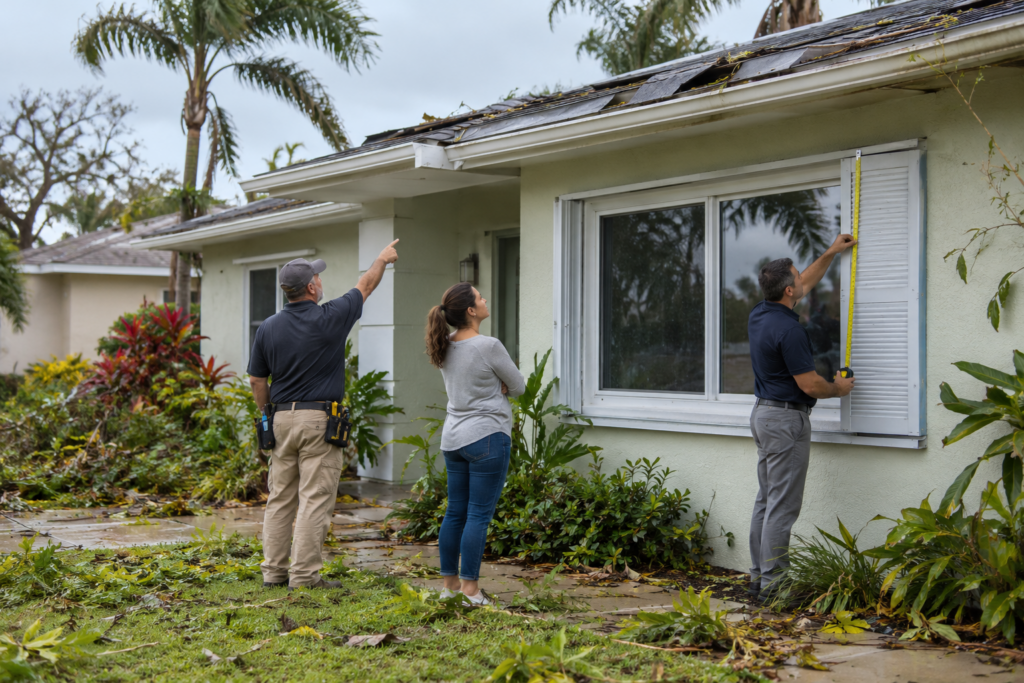
A useful file commonly includes the full policy and endorsements, application materials, notice of loss, proof-of-loss forms, claim submissions, photographs with original metadata, inspection reports, estimates, invoices, receipts, payment records, emails, text messages, call logs, and letters from the insurer. Keep envelopes and attachments with the communications they accompanied.
For each important document, identify who prepared it, who reviewed it, when it was sent, and what information was available at that time. If a contractor, public adjuster, medical provider, employee, family member, or other participant supplied information, preserve the original exchange. Reliance on another person does not automatically eliminate responsibility, but authorship and review may be important facts.
Do not backdate, rewrite, or “clean up” records. Preserve the unedited photo, file, email, or message even if it contains a mistake. If business systems automatically delete data, tell counsel how the system works so lawful preservation can be considered.
Separate three timelines
Many confusing files become clearer when divided into three chronologies:
- The loss timeline: the condition before the event, what occurred, when damage was noticed, and what emergency work followed.
- The claim timeline: notice, inspections, estimates, requested information, payments, denials, and appeals or supplemental submissions.
- The investigation timeline: special-investigations contact, interview requests, referrals, subpoenas, and government communications.
Keeping those tracks distinct helps show whether an apparent contradiction reflects different events, a genuine error, or an allegation requiring closer review. It also prevents a policy dispute from being described as criminal conduct without identifying the statement, speaker, timing, and claimed materiality.
One matter may require different kinds of counsel
A lawyer handling a civil coverage dispute may focus on policy interpretation, claim benefits, and contractual procedures. Criminal defense counsel focuses on exposure from alleged false statements, interviews, subpoenas, searches, and possible charges. Some matters require coordination between those roles so that a position taken in one proceeding does not create an avoidable problem in another.
Beaton Law Firm’s insurance-fraud defense practice can assess whether a communication reflects an ordinary coverage disagreement, a fraud-focused inquiry, or overlapping proceedings. A consultation can also identify which original records should be preserved and which deadlines require attention. No particular outcome can be promised.
Get advice before a detailed interview or production
If a claim was denied, begin with the actual policy language and written explanation. If fraud is alleged, identify the exact statement or document being questioned, who prepared it, and what the sender is asking you to do. Keep all versions and do not alter the underlying file.
This article provides general information, not legal advice. Insurance contracts, civil remedies, criminal statutes, and response obligations vary with the policy, claim, forum, and facts. Reading this page or contacting the firm does not create an attorney-client relationship unless the firm agrees to represent you.